FBAR vs FATCA Form 8938: Key Differences Every U.S. Taxpayer Abroad Must Know

Understanding FBAR vs FATCA Form 8938 is essential for every U.S. citizen or green card holder living abroad, including the growing community of Americans in Israel. Both reports target foreign financial assets, yet they are governed by different laws, submitted to different agencies, carry different thresholds, and cover different types of assets. Filing the wrong form — or missing one entirely — can trigger penalties that dwarf the account balances you failed to report. This guide breaks down everything you need to know so you can stay fully compliant with both obligations.
—
What Are FBAR and FATCA Form 8938?
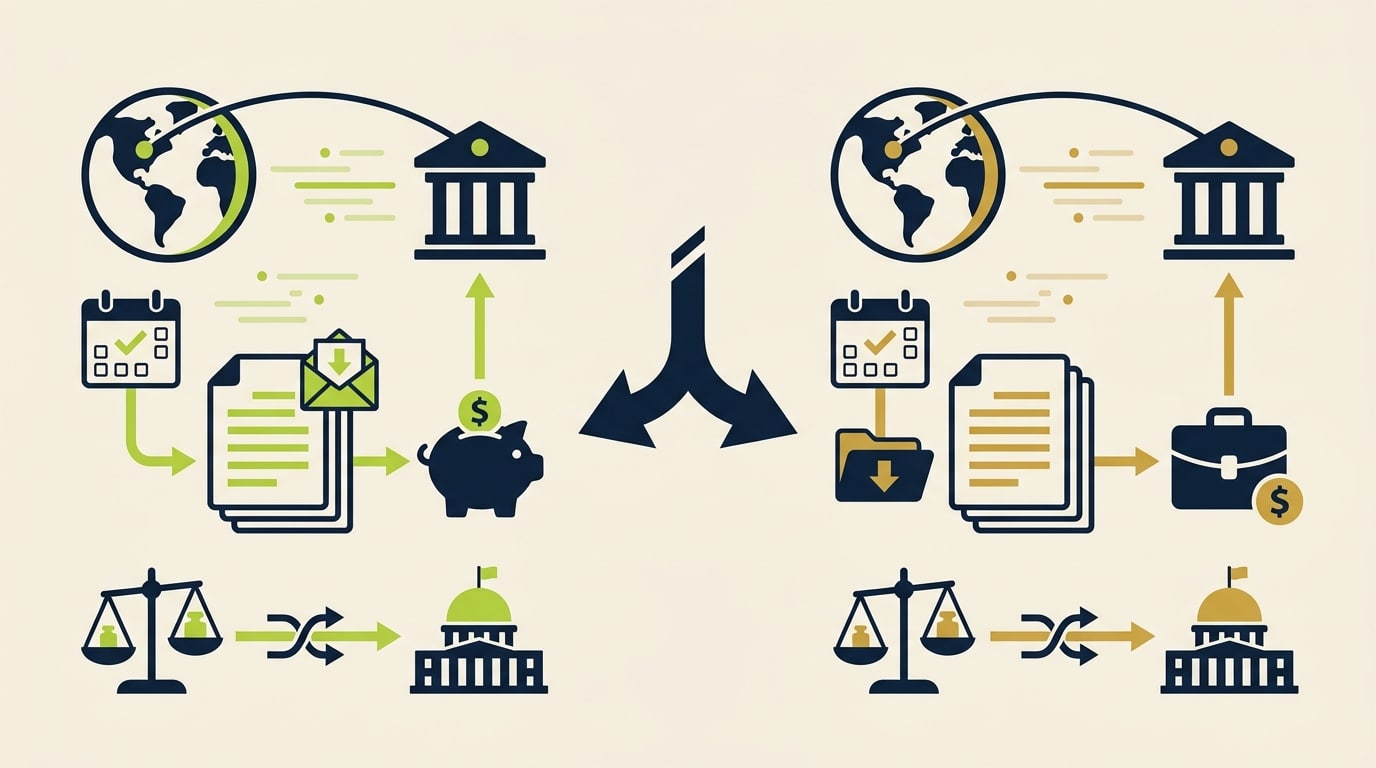
FBAR (Foreign Bank Account Report), officially known as FinCEN 114, is a filing requirement under the Bank Secrecy Act. It is administered by the Financial Crimes Enforcement Network (FinCEN), a bureau of the U.S. Department of the Treasury. You can learn more about FinCEN’s mandate at FinCEN.gov.
FATCA Form 8938 is a disclosure requirement created by the Foreign Account Tax Compliance Act (FATCA), enacted in 2010. It is administered by the Internal Revenue Service (IRS) and filed as an attachment to your annual U.S. federal tax return. Full guidance is available at IRS.gov.
Although both reports concern foreign financial accounts, they exist for different regulatory purposes. FBAR targets financial crime and money laundering. Form 8938 targets tax compliance. This means the two reports overlap significantly — but not completely — and most Americans with substantial foreign assets must file both.
For a deep dive into the FBAR requirement, visit our comprehensive FBAR Guide. For details on FATCA obligations, see our FATCA Reporting page.
—
FBAR vs FATCA: The Core Differences at a Glance
One of the most effective ways to understand FBAR vs FATCA Form 8938 is to lay the two requirements side by side. The table below summarizes the most critical differences:
| Feature | FinCEN 114 (FBAR) | FATCA Form 8938 |
|---|---|---|
| Administered by | FinCEN (Dept. of Treasury) | IRS |
| Filed with | Separate FinCEN BSA e-filing system | Attached to Form 1040 / 1040NR |
| Filing deadline | April 15 (auto-extension to Oct 15) | Same as tax return (April 15, with extensions) |
| Threshold — single/MFS (domestic) | $10,000 aggregate at any point | $50,000 on last day OR $75,000 at any point |
| Threshold — living abroad (single) | $10,000 aggregate at any point | $200,000 on last day OR $300,000 at any point |
| Threshold — married filing jointly abroad | $10,000 aggregate at any point | $400,000 on last day OR $600,000 at any point |
| Penalty — non-willful | Up to $10,000 per violation | Up to $10,000 per failure to disclose |
| Penalty — willful | Greater of $100,000 or 50% of account balance | Up to $50,000 (continuing failure) + criminal |
| Criminal penalties | Yes | Yes |
| Covers signatory authority (no ownership) | Yes | No |
| Covers direct foreign investments | No | Yes |
Important: Once you cross the applicable threshold for either form, both may be required. Filing one does not substitute for the other.
—
Reporting Thresholds Explained in Detail
The threshold rules are where FBAR vs FATCA confusion most commonly arises. Understanding them precisely can prevent costly mistakes.
FBAR threshold: If the aggregate value of all your foreign financial accounts exceeds $10,000 at any single moment during the calendar year, you must file — even if each individual account holds far less than $10,000. This is a very low bar that catches many Americans living in Israel who hold an ordinary Israeli checking account alongside a savings or pension account.
FATCA Form 8938 threshold: The threshold depends on your filing status and where you live:
- U.S.-resident filers (single or married filing separately): Report if total exceeds $50,000 on the last day of the year, or $75,000 at any point.
- U.S.-resident filers (married filing jointly): $100,000 on the last day, or $150,000 at any point.
- Filers living abroad (single or MFS): $200,000 on the last day of the year, or $300,000 at any point.
- Filers living abroad (married filing jointly): $400,000 on the last day, or $600,000 at any point.
Because the FBAR threshold is dramatically lower, many Americans who do not need to file Form 8938 will still be required to file an FBAR. The reverse is far less common.
Worked example: An American living in Tel Aviv holds a checking account (average balance ₪25,000), a savings account (average balance ₪50,000), and a small brokerage account (average balance ₪15,000). Even if none of these individually exceeds $10,000, their combined value on any single day likely does — triggering an FBAR obligation. If the combined total does not reach the $200,000 FATCA threshold at year-end or $300,000 at any point during the year, Form 8938 may not be required — but the FBAR absolutely is.
—
Which Accounts and Assets Are Covered?
This is where FBAR and FATCA Form 8938 diverge most significantly. The asset coverage rules determine whether you file one form, the other, or both.
| Asset / Account Type | FBAR (FinCEN 114) | FATCA Form 8938 |
|---|---|---|
| Foreign bank account (savings, checking) | ✅ Yes | ✅ Yes |
| Foreign brokerage / investment account | ✅ Yes | ✅ Yes |
| Life insurance with cash value (foreign) | ✅ Yes | ✅ Yes |
| Foreign trust fund | ✅ Yes | ✅ Yes |
| Account at U.S. entity in a foreign country | ✅ Yes | ❌ No |
| Signatory authority only (no ownership) | ✅ Yes | ❌ No |
| Direct foreign investment (not via account) | ❌ No | ✅ Yes |
| Interest in a foreign partnership | ❌ No | ✅ Yes |
| Stock or securities in a foreign entity | ❌ No | ✅ Yes |
| Real estate held directly | ❌ No | ❌ No |
| Real estate via a foreign entity | ❌ No | ✅ Reflected via stock/rights |
| Foreign government social insurance | ❌ No | ❌ No |
| Cash, jewelry, art held directly | ❌ No | ❌ No |
Key takeaways:
- FBAR reaches further into accounts where you have signatory authority but no ownership, and into accounts held at foreign branches of U.S. banks.
- Form 8938 reaches further into direct investments and interests in foreign entities that do not sit inside a formal account.
- Both forms exclude real estate held directly and foreign social insurance programs.
—
Penalties for Non-Compliance: Why the Stakes Are So High
The penalty structure is severe enough to warrant careful attention in any FBAR vs FATCA Form 8938 comparison. These are not theoretical risks — the IRS and FinCEN have actively pursued enforcement for over a decade.
FBAR Penalties
- Non-willful violation: Up to $10,000 per account per year. A single unreported Israeli bank account for three years could mean $30,000 in penalties.
- Willful violation: The greater of $100,000 or 50% of the highest balance in the account — per account, per year. These penalties can easily exceed the account balance itself.
- Criminal prosecution: Possible for willful violations, with fines up to $250,000 and imprisonment up to five years.
Form 8938 Penalties
- Failure to file: $10,000 penalty at the outset. If you still fail to file after IRS notice, an additional $10,000 for every 30-day period, up to a maximum of $60,000.
- Understatement of tax: A 40% penalty applies to any tax understatement attributable to an undisclosed foreign financial asset.
- Criminal penalties also apply for fraudulent non-disclosure.
Understanding these penalties underscores why professional guidance matters. Visit our services page to learn how we help Americans in Israel navigate both filing requirements efficiently and accurately.
—
Common Mistakes Americans in Israel Make
Mistake 1: Treating FBAR and Form 8938 as interchangeable
They are legally distinct. Filing Form 8938 does not satisfy your FBAR obligation, and filing an FBAR does not satisfy Form 8938. Each must be filed independently through its own process.
Mistake 2: Overlooking signatory authority
If you are a signatory on a family member’s Israeli bank account or on a business account, you may have an FBAR obligation even if you have no beneficial ownership in the funds. Many dual-career couples and business owners miss this entirely.
Mistake 3: Miscalculating the FBAR aggregate threshold
The $10,000 FBAR threshold applies to the aggregate of all foreign accounts on any single day of the year — not just the year-end balance. A temporary deposit, a transfer, or a large paycheck can push you over the threshold even if your year-end balances are modest.
Mistake 4: Ignoring the U.S.-Israel tax context
Americans living in Israel benefit from the U.S.-Israel Tax Treaty, which may affect how income from Israeli accounts is taxed — but it does not eliminate FBAR or FATCA reporting obligations. You may also be entitled to a Foreign Tax Credit for taxes paid to Israel, which can reduce double taxation. However, these treaty benefits and credits are entirely separate from your reporting obligations under FBAR and Form 8938.
Mistake 5: Failing to address prior-year non-compliance
If you have never filed FBAR or Form 8938 and have been required to do so, voluntary disclosure programs exist that may significantly reduce your penalty exposure. The IRS Streamlined Filing Compliance Procedures, in particular, were designed for non-willful non-filers living abroad. Acting sooner rather than later is strongly advisable — penalties and interest accumulate over time.
—
How to File Each Form
Filing FBAR (FinCEN 114): FBAR must be filed electronically through the BSA E-Filing System maintained by FinCEN — it cannot be mailed with your tax return. The deadline is April 15, with an automatic extension to October 15. Visit FinCEN.gov for the official e-filing portal. No extension request is required; the extension is granted automatically.
Filing FATCA Form 8938: Form 8938 is attached to your annual Form 1040 (or 1040NR) and submitted through the normal tax filing process — either electronically or by mail. The filing deadline matches your tax return deadline, including any extensions granted by the IRS. Detailed instructions are available at IRS.gov. If you file late or amend a prior return, Form 8938 must be included with the amended filing.
—
Summary: FBAR vs FATCA — Do You Need to File One or Both?
Most Americans living in Israel with local bank accounts, savings, investment accounts, or pension funds will need to assess both obligations every year. As a practical rule of thumb:
- If your foreign accounts exceeded $10,000 in aggregate at any point during the year → file FBAR.
- If your foreign financial assets exceeded the applicable FATCA threshold for your filing status and residency → file Form 8938.
- If both thresholds are crossed → file both.
Neither form is optional, and neither exempts you from the other. The FBAR vs FATCA Form 8938 distinction matters not just for compliance purposes but for understanding exactly what the U.S. government is asking you to disclose and why. FBAR exists to detect financial crime; Form 8938 exists to ensure that income from foreign assets is properly taxed.
If you are unsure about your obligations — whether you’ve been living abroad for decades or have just moved to Israel — the consequences of getting it wrong are significant enough to warrant professional advice.
Ready to get compliant? Contact our team at tax4us.co.il — we specialize in helping U.S. citizens in Israel navigate FBAR, FATCA, and all aspects of American expat tax compliance.